
Disclosure: I receive a referral reward for anyone who signs up using my code.
Looking for cheaper alternatives to traditional health insurance? You’re not alone. With rising premiums, confusing coverage, and paying hundreds each month for something you might only rarely use, it’s natural to wonder if there’s a better option.
For nearly a year, I debated leaving traditional health insurance. As a self-employed individual with no employer coverage, my ACA plan was costing me nearly $500 per month just to cover myself.
Eventually, I decided I’d had enough.
I canceled my traditional health insurance and joined CrowdHealth instead.
Why I Walked Away From Traditional Health Insurance
Leaving traditional health insurance wasn’t an easy decision.
For a long time, I was afraid to step outside the conventional insurance system. I had worked in the insurance industry for 17 years prior to having my son, so it was just something I took for granted in a lot of ways and didn’t know much about alternatives.
What happens if I get seriously sick? What if I need an expensive prescription? What if an unexpected emergency turns into a massive medical bill?
Those are legitimate concerns, and they kept me paying hundreds of dollars every month.
But eventually, the cost and my personal experiences pushed me to reconsider.
As a stay-at-home mom who is self-employed, I was responsible for finding and paying for my own health coverage. My individual ACA plan was costing me close to $500 per month.
That’s nearly $6,000 a year just for premiums.
Here’s what made it even more frustrating: I rarely visited the doctor outside of routine bloodwork.
Then came an experience that really changed my perspective.
After experiencing a miscarriage, I received a call from BCBS questioning why I had visited the emergency room. They had sent me a bill for $3,000, so I already knew it was outrageously expensive. They had the gall to tell me that I should have used urgent care instead to keep costs down. It was my midwife who had told me to visit the ER if there was any hope of saving the baby, so I would do it all over again in an instant, no thanks to any support from BCBS!
That phone call from them was the final straw for me.
I started asking myself whether continuing to pay so much into a system that left me feeling frustrated was really the best option.
What Is CrowdHealth?
CrowdHealth is a community of people who help pay each other’s medical bills.
You pay a monthly membership fee, plus a separate monthly contribution toward other members’ bills.
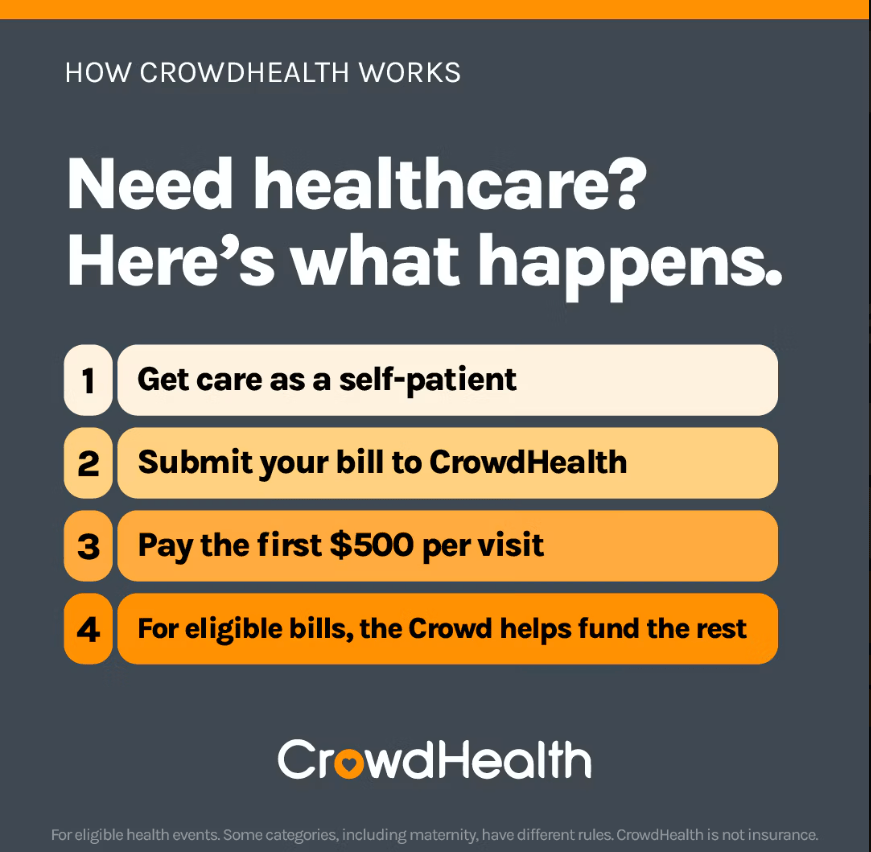
Say you break your arm. You’ve got your own care advocate – think of them as your healthcare sidekick – to help you through the whole process. You get the care you need, pay the cash-pay rate (which is almost always way lower than the inflated insurance rate), then send CrowdHealth the bills. You pay your portion, and as long as it’s an eligible medical need, they ask the community to help fund the rest.
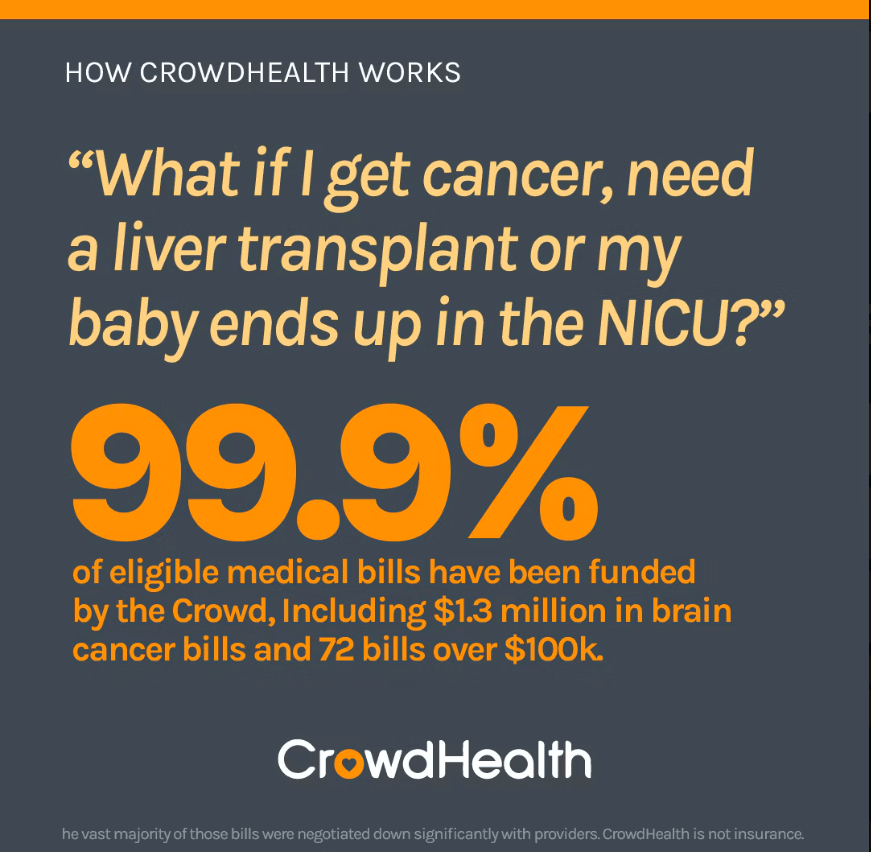
And it works for the really big stuff too, like one member’s $3M bill for their baby’s NICU stay.
To date, 99.9% of eligible bills have been funded. The typical cost is 30-70% less than you’d pay for traditional health insurance.
It’s not insurance. That’s the whole point.
The idea of being part of a proactive healthcare community instead of simply paying into a traditional insurance system appealed to me.
I decided to take the leap.
How does it cost so little?
Lower prices for care. Self-pay prices are often significantly lower than the prices billed through insurance. CrowdHealth helps members find fairly priced care and negotiates medical bills, so the crowd has less to fund.
A community committed to healthy living. When members join, they agree to a set of commitments that support a healthy lifestyle. A healthier community helps keep healthcare costs lower for everyone.
A waiting period for preexisting conditions. Expenses related to preexisting conditions have a two-year waiting period before they become eligible for crowdfunding. This helps keep contributions manageable while members build a history of supporting one another.
But what about the big stuff?
Is CrowdHealth Right for Everyone?
Here’s where I want to be very transparent.
CrowdHealth is NOT traditional health insurance, and it shouldn’t be treated as a one-for-one replacement for an ACA-compliant policy.
Healthcare sharing and crowdfunding arrangements can have different eligibility requirements, limitations, and payment processes than regulated health insurance.
Before making a switch, take time to understand:
– What types of medical expenses are eligible for sharing.
– How pre-existing conditions are handled.
– What happens with emergency room visits and hospitalizations.
– How prescription medications are handled.
– What your financial responsibility could be for unexpected medical expenses.
– Whether the arrangement meets your needs and offers the protections you require.
Don’t make a healthcare decision based solely on someone else’s monthly savings.
Do your homework, read the membership guidelines, and make sure you understand what you’re joining.
I’m sharing my personal experience, not telling everyone to cancel their insurance.
The biggest immediate difference for me has been the monthly cost.
I’m paying less than half of what I was paying for my previous ACA plan.
Beyond the financial difference, I genuinely enjoy being part of a movement that encourages people to become more proactive about their health.
Is it a perfect solution for everyone? No.
For someone who was frustrated with the cost of traditional coverage and wanted to explore another approach, I’m glad I took the time to investigate it.
If you’re staring at your open enrollment options, wondering how you’re going to make the numbers work, I think it’s worth putting CrowdHealth on your research list.
Want to Learn More About CrowdHealth?
If you’re self-employed, paying high monthly health insurance premiums, or simply curious about alternatives to traditional health insurance, I’d encourage you to look into it.
I know how intimidating it can feel to step outside the system. I spent a long time worrying about all the what-ifs, too.
If you decide CrowdHealth is something you’d like to explore, I have a referral code that will save you money. You’ll get a discounted rate of $99/month for your first three months. ***Other fees may apply depending on the plan you select.
Use my referral code: EMILYA
If you’re ready to investigate a different approach to healthcare and why I consider myself to now be “delightfully uninsured”, start here:
Explore CrowdHealth
Use referral code EMILYA during signup to receive the first three months’ savings offered through my referral.
Still have questions? Drop a comment or email me at theplankingtraveler@gmail.com.

